The spreadsheet was built for a different market. The 2026 season requires something else. Tighter margins, a rewritten safety net, more volatility than most producers have dealt with in years — your clients already know the pressure. This report is about what it means for the advisors sitting across the table from them.
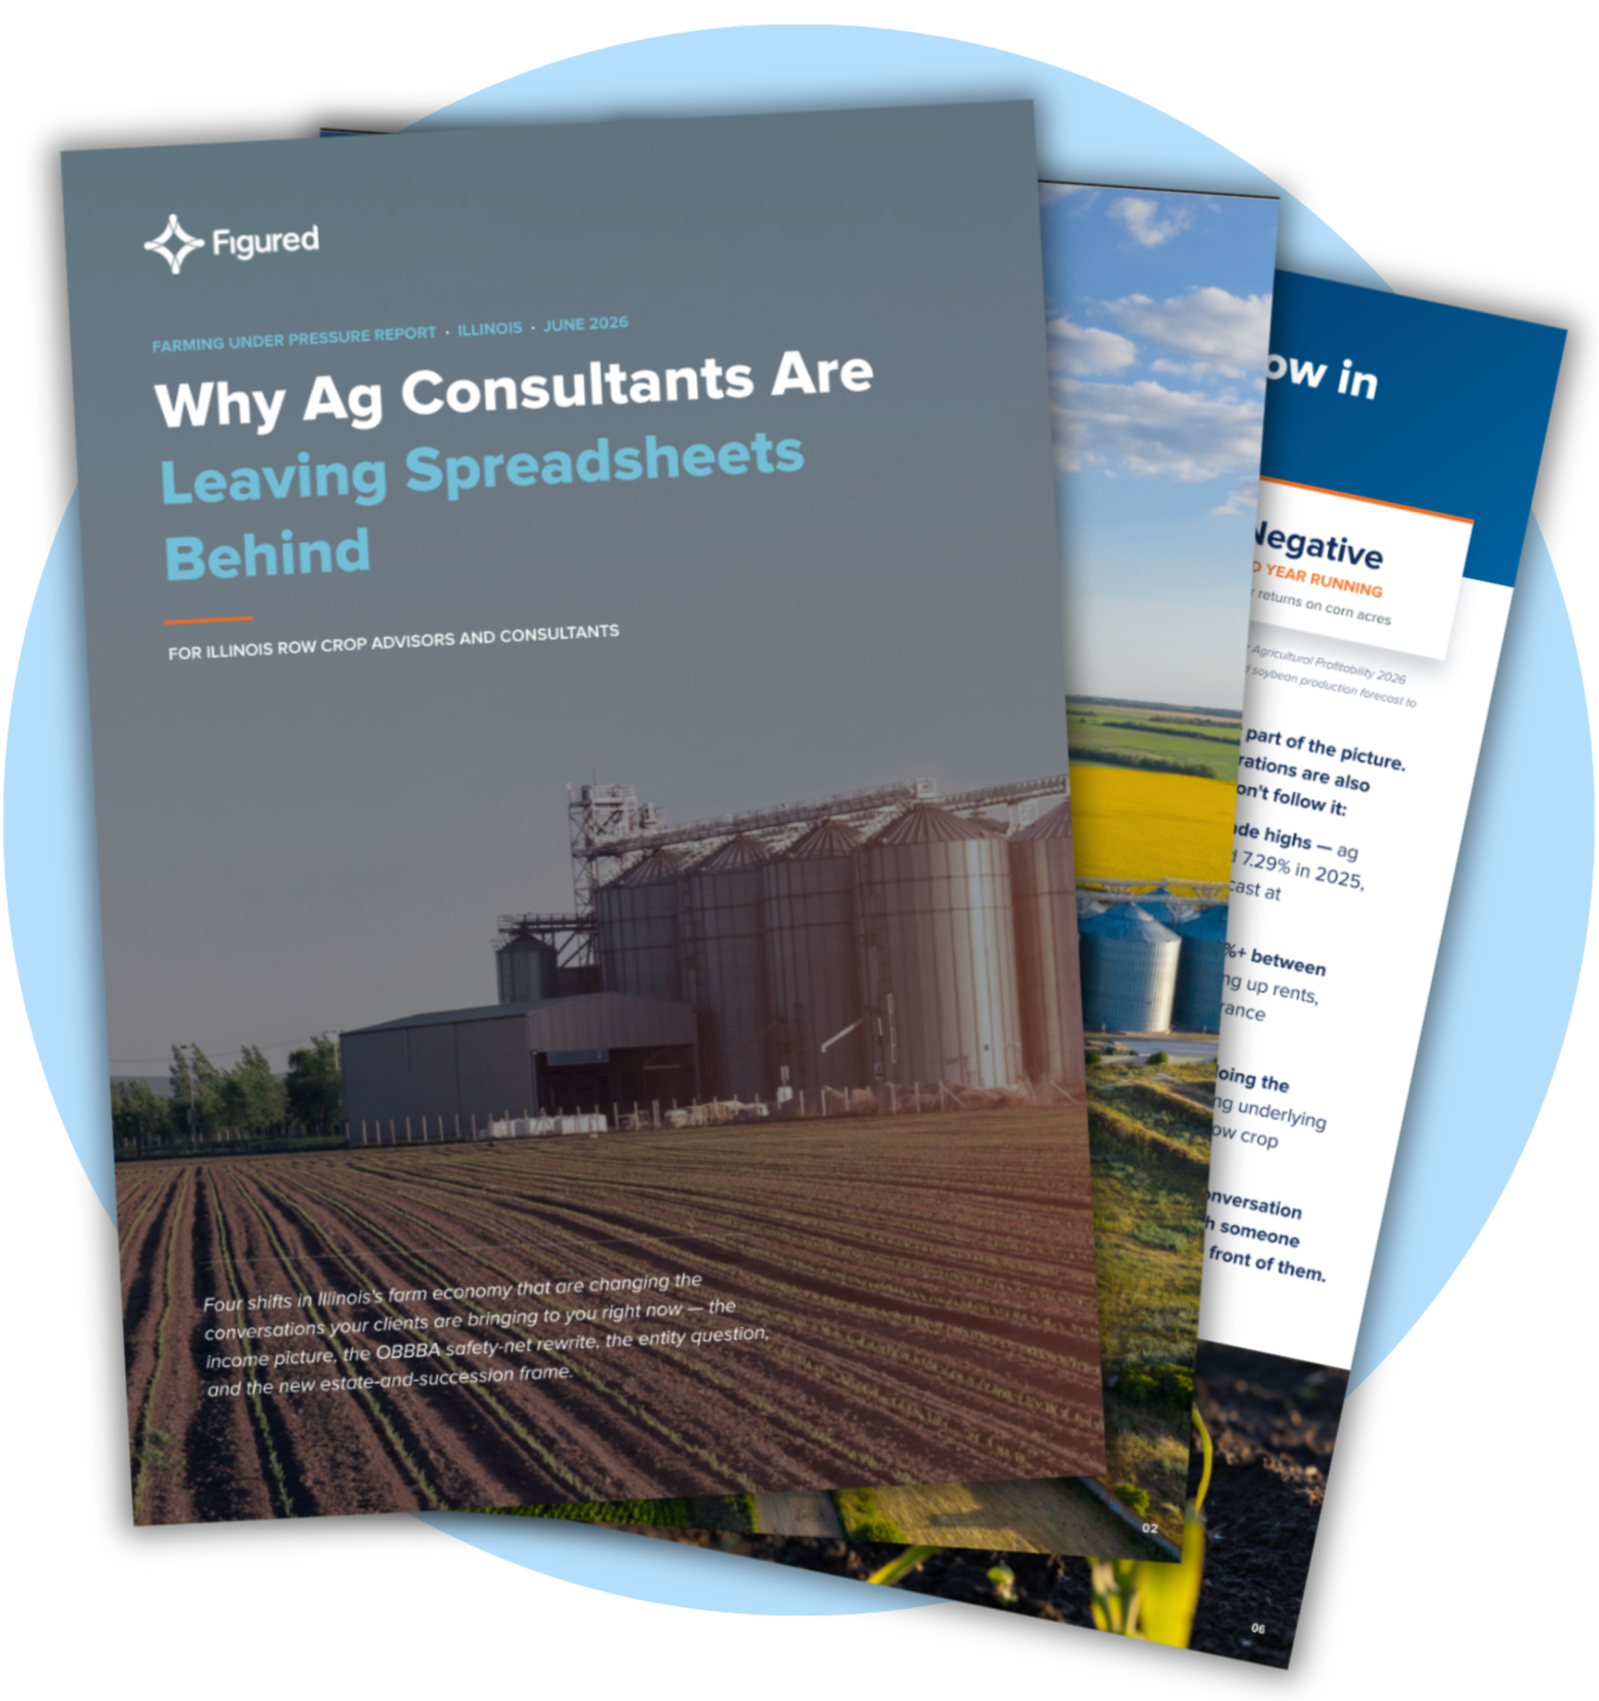
What You'll Learn
A grounded picture of what's driving client conversations right now — income pressure, OBBBA payment changes, lender behavior tightening at the sector level, and structure and succession questions that can't wait for year-end.
It's not an expertise problem. When the same market move hits multiple clients at once, there's no way through a spreadsheet-based workflow that isn't measured in days. The ceiling isn't your ability — it's the tool.
You'll hear directly from advisors who've changed what their client work runs on — what shifted, what they didn't expect, and what it meant for specific client outcomes when the numbers were already there.
Live data from QuickBooks Online or Xero. Scenario modeling in minutes, not days. Bank-ready financials before the bank calls. How Figured fits into an existing workflow — and what it makes possible when conditions move fast.
Who It's For
What's Inside